Mirovα, Creating Sustainable Value - October 2026
Key Events - September 2026
Central banks: The Fed and the ECB have raised their interest rates by 25 basis points, in response to economic activity proving more resilient than anticipated and a resurgence in inflation. The Bank of Japan is continuing its monetary tightening.
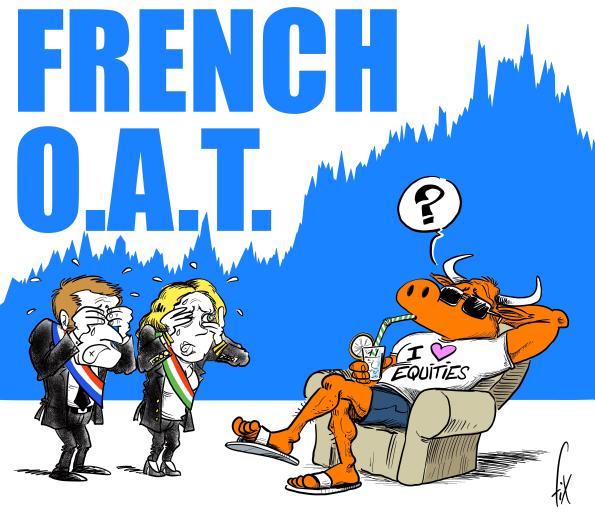
Fixed income: Yields on government bonds have risen sharply and in a synchronised manner. This has spread to credit spreads from mid-September onwards. France is the focus of concerns, with its spread against Germany reaching 140bps during the month.
Equities: US tech stocks are acting as a safe haven. The Nasdaq rose by around 2% over the month. Interest rates and energy prices weighed on the rest of the market.
Number of the month
Macro Outlook
United States: As the main driver of global growth, the US economy is benefiting from solid household consumption and massive investment in AI-related technology. However, whilst the market is still pricing in three further rate rises by the end of the first half of 2027, our base-case scenario anticipates only one or two.
Eurozone: The European economy is showing resilience but remains deeply weakened by rising energy costs and tightening credit conditions. The ECB finds itself in an uncomfortable position and is likely to limit its tightening to avoid exacerbating financial fragmentation in the region.
France: The country has now emerged as the eurozone’s main weak point, given its public debt trajectory and political uncertainties.
China: the central bank has embarked on a easing cycle; the next source of support could come from fiscal policy.
The Long View - Markets turn to Space
- An economy transformed by falling costs
- Telecommunications: towards a hybrid model
- Orbital data centres: a long-term option
- Mixed ESG record and insufficient regulation
The shift from experimentation to predictive discovery. Investing Insights from the Sustainable Equity Team
Climate, Nature and Sustainability Report (LEC 29, TCFD, TNFD)
